What is bed and breakfast home insurance?
Running a B&B changes how your home is occupied and the risks an insurer needs to consider. Regularly welcoming paying guests may fall outside the terms of an ordinary home insurance policy, particularly if the insurer has not been told about the business use.
Bed and breakfast insurance provides household buildings and contents cover while recognising that part of your home is used to accommodate paying guests.
We’ll ask about your property, the number of guest bedrooms and how your B&B operates.
This allows us to find cover that reflects both your home and its use as guest accommodation.
Is our B&B home insurance suitable for you?
We can generally consider owner-occupied B&Bs where:
- You live at the insured property.
- The property has no more than seven bedrooms in total.
- At least one bedroom is retained for you as the owner.
- Up to six bedrooms are used for paying guests.
- No more than two paying guests occupy each letting bedroom, excluding infants.
- Rooms are advertised directly or through platforms such as Airbnb or Vrbo.
- The property is of standard, listed or non-standard construction.
Acceptance remains subject to the individual property, its facilities, how it is occupied and the insurer’s underwriting criteria.
What does bed and breakfast insurance cover?
The precise cover will depend on the policy offered.
Your quotation and policy documents will show the applicable limits, exclusions and endorsements before you buy.
What we provide
What isn't included?
- Business-related liability unless expressly included in the policy offered.
- Malicious damage or theft by paying guests.
- Wear and tear, gradual deterioration or damage that occurred before the policy began.
- Lost booking income or business interruption.
- Accidental damage caused by paying guests unless expressly confirmed.
- you are only covered up to the maximum claims limits shown on your schedule
- you are responsible for any excesses stated in your policy
- any exclusions or restrictions shown by endorsement in your schedule
Does B&B insurance include public liability cover?
Public liability arising from operating a B&B is not automatically included under every household policy.
Where liability cover is available, its scope and indemnity limit will be shown in the quotation and policy documentation.
You should check that the cover offered is appropriate for your business and meets any licensing or regulatory requirements that apply to your property.
Insurance for listed and non-standard B&B properties
B&Bs are often operated from properties that do not fit neatly within standard home insurance criteria.
When searching our panel for suitable cover, we’ll consider both the construction of your property and how it is used as a B&B.
We can consider a variety of homes, including:
- Listed buildings.
- Barn conversions.
- Timber-framed properties.
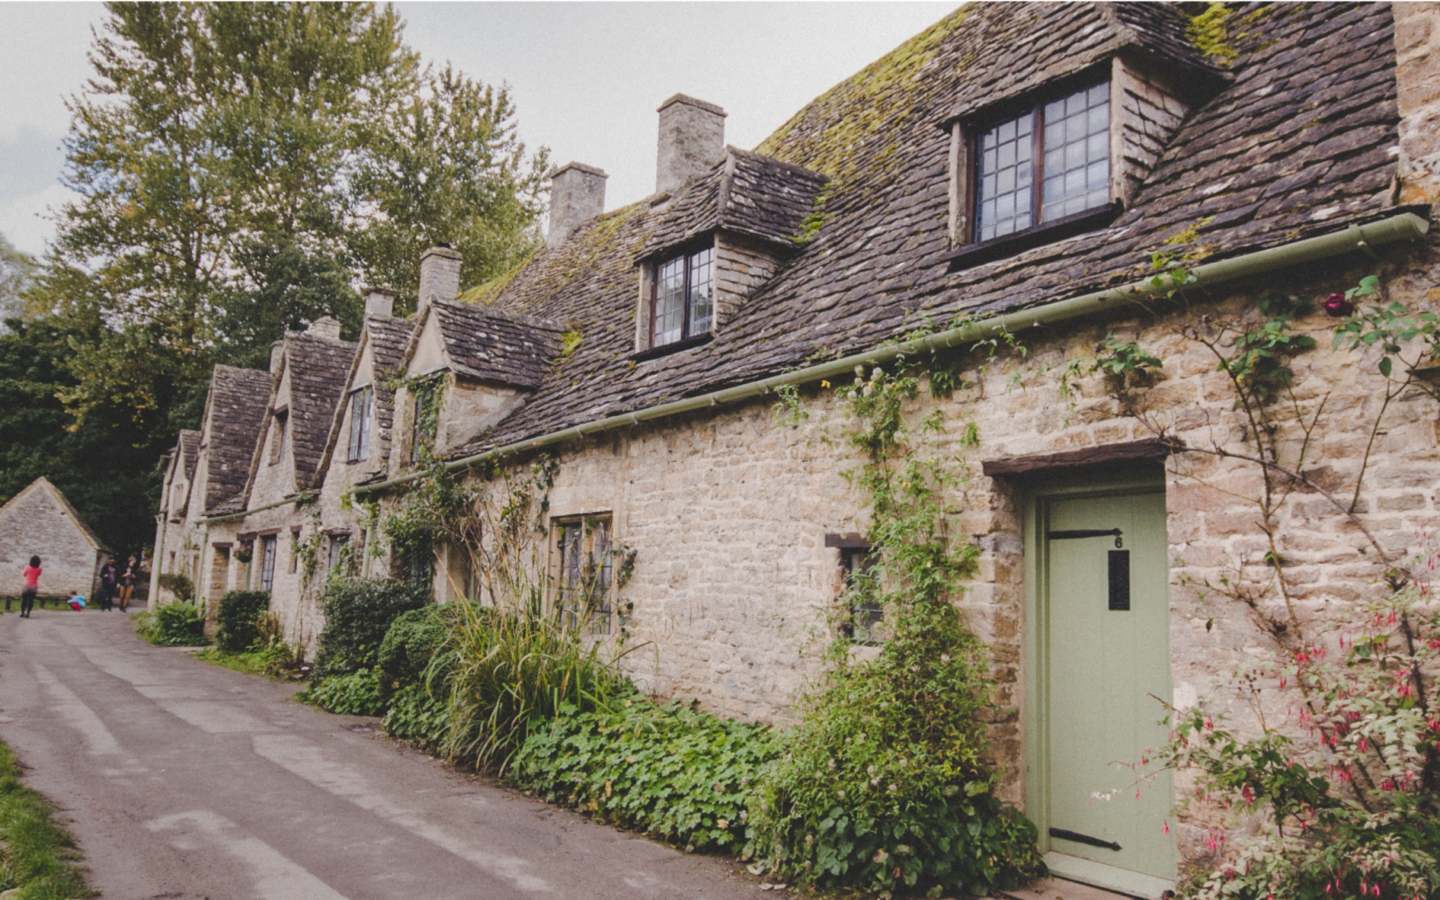
- Rural cottages.
- Older and unusually constructed properties.
- Homes with high rebuild values.
How much does bed and breakfast insurance cost?
There is no single price for B&B insurance because every property and business arrangement is different.
Your premium will reflect the home being insured, the number of guests accommodated and the level of cover selected.
Factors that may affect the cost include:
Your property
- Location and local claims history.
- Rebuild cost.
- Construction type and age.
- Listed status.
- Security and fire-safety measures.
- Previous insurance claims.
How you run your B&B
- The number of letting bedrooms.
- The maximum number of paying guests.
- How frequently rooms are occupied.
- Whether bookings are taken directly or through an online platform.
- The buildings and contents cover required.
- Any optional cover selected.
The quickest way to establish the likely cost is to complete an online quote using accurate information about your property and its use.

Frequently Asked Questions
You should tell your insurer before accepting paying guests. An ordinary home insurance policy may restrict or exclude business use and paying guests. Specialist B&B home insurance records how the property is used and provides household cover based on that information.
We can generally consider properties with up to seven bedrooms in total, provided that at least one bedroom remains for the resident owner. This means up to six bedrooms may be used for paying guests, subject to underwriting.
Up to two paying guests per letting bedroom can generally be considered, excluding infants. The total occupancy must also be appropriate for the size, layout and facilities of the property.
Yes. Properties advertised through Airbnb, Vrbo and similar booking platforms can be considered. You must accurately disclose how the rooms are advertised and used when requesting a quote.
Public liability connected with running a B&B is not automatically included under every policy. Where it is available, the extent of cover and applicable indemnity limit will be stated in your quotation and policy documents.
Malicious damage or theft by paying guests is excluded. Accidental damage caused by paying guests is not included under every policy and should only be considered covered when it is expressly confirmed in your quotation and policy documents.
No. Guests are responsible for arranging insurance for their own possessions. The contents section of your policy covers eligible belongings belonging to you and other insured members of your household.
No. The household B&B insurance options described on this page do not provide cover for lost booking income or business interruption.
We can consider listed buildings, barn conversions and various non-standard construction types used as owner-occupied B&Bs.
Acceptance and cover will depend on the property, its rebuild cost and how it is operated.
The price depends on factors including the property’s location, construction, rebuild value, claims history, number of guest rooms and the cover selected.
Completing a quote will provide a price based on your particular circumstances.
Why choose Intelligent Insurance for B&B cover?
- Specialist experience arranging insurance for homes with paying guests.
- Defaqto 5-Star-rated buildings and contents cover.
- Cover available for listed and non-standard properties.
- Clear limits, exclusions and endorsements provided before purchase.
- Support from our UK-based customer service team.
Tell us about your property and how you accommodate paying guests.
Our UK-based team can help with the information we need about your B&B.
Still have questions? Visit our help centre
Policy Documents
The documents below provide information about our core buildings and contents insurance. If you’re currently insured with us, you’ll find the documents applying to your policy in MyAccount.
How to make a claim for your B&B
If you need to make a claim, follow these three steps:

Step One – Check Your Policy
Find your insurer’s claims contact details in your policy document or Schedule. Always have your policy number to hand, as it helps your insurer’s claims team quickly identify you and assist you without delay.

Step Two – Report the Incident
Call your insurer’s claims team as soon as the incident occurs. Provide a brief description of what happened and, if applicable, notify the police within seven days for incidents like theft or malicious damage.

Step Three – Submit Your Claim
If required, complete and return the claim form along with supporting documents (receipts, photos, etc.) within 30 days. This ensures a smooth, timely processing of your claim.
*We may not be able to quote in all circumstances. Cover limits/restrictions and/or conditions may apply to the policy. These are clearly detailed prior to purchase, and in the policy documentation for you to determine if the cover is suitable for your needs.
Home Insurance Specialists names you can trust