Find out when to enter 100% for one construction category and how to describe a home built using different methods.
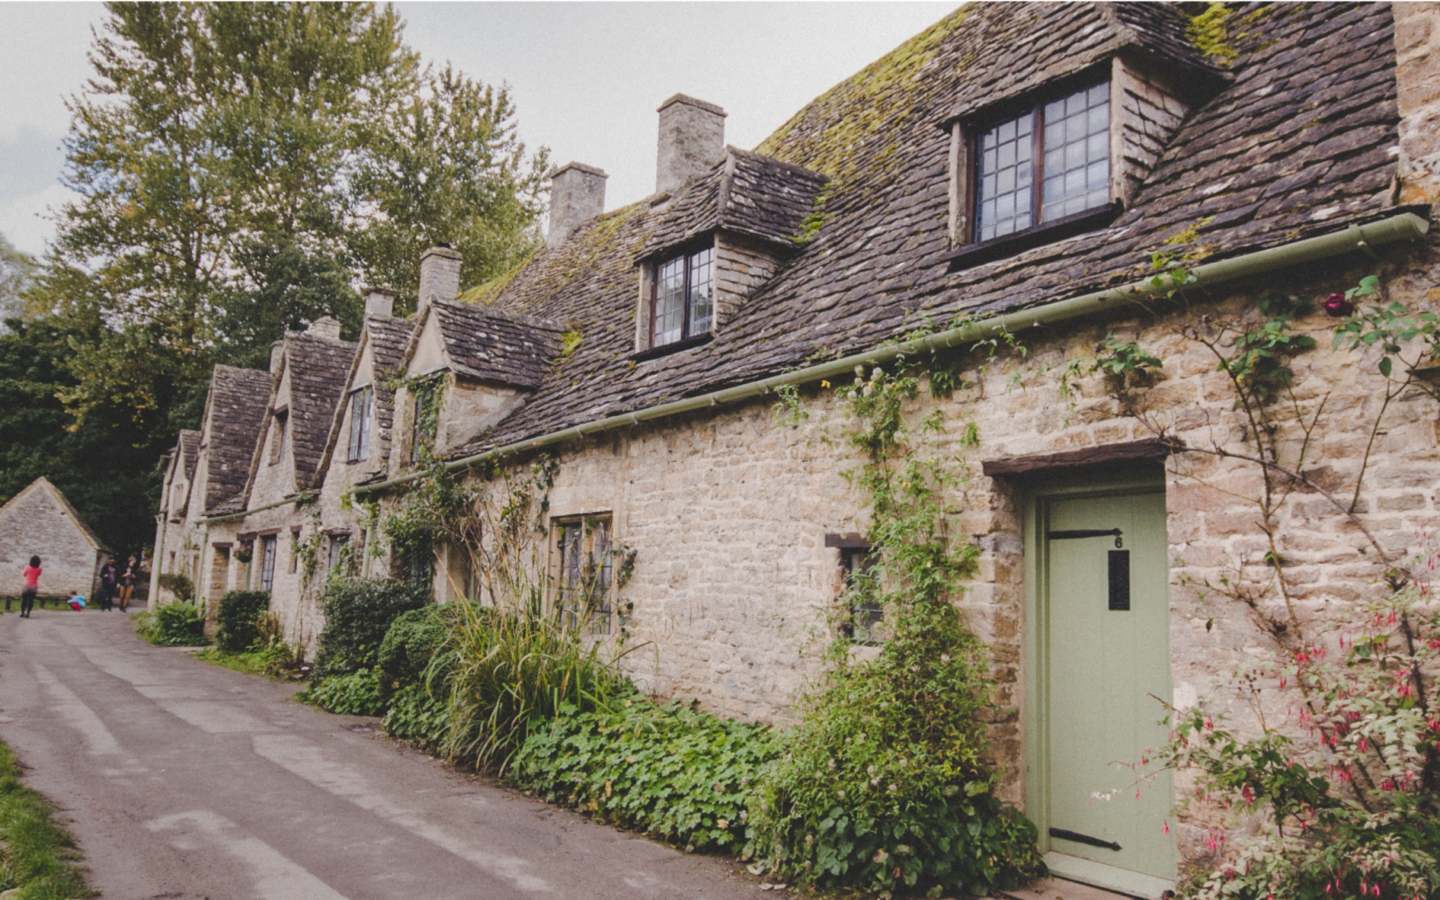
In home insurance, standard construction usually means brick or stone walls with a pitched slate or tile roof. Different materials, structural frames or roof coverings may fall outside an insurer’s usual criteria.
That does not automatically make your home defective, uninsurable or more expensive to insure. Different insurers assess construction differently, so the important details are the actual structure, materials, condition and rebuild cost.
As a specialist broker, we work with a panel of insurers that can consider a range of non-standard properties. Acceptance and policy terms depend on your individual home and circumstances.
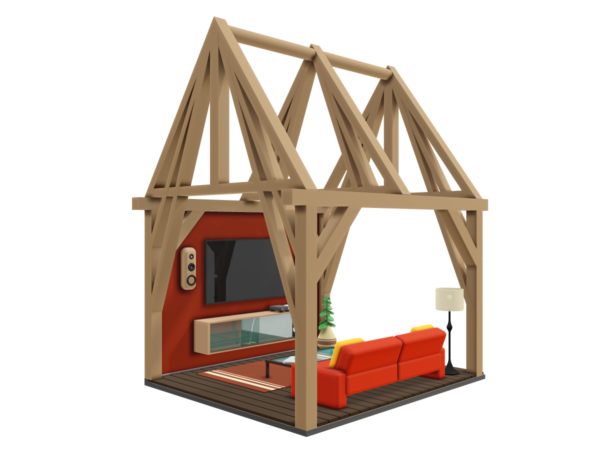
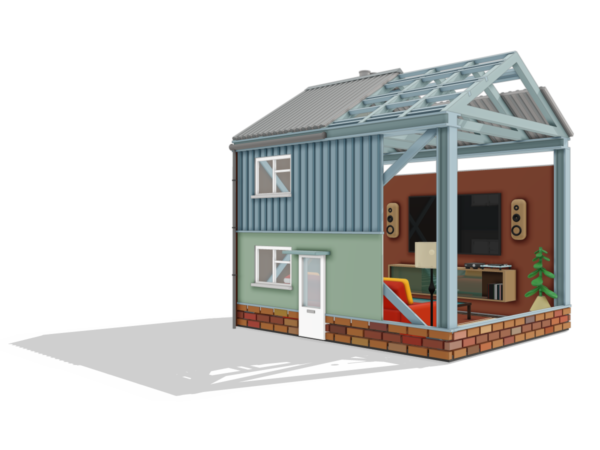
Properties with a structural timber frame, including those with a brick exterior.
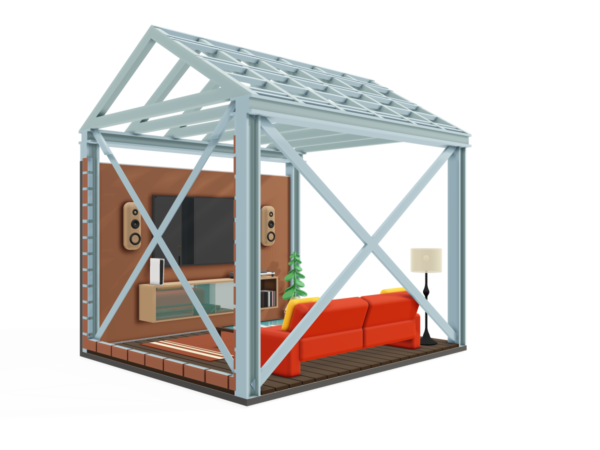
Homes where steel forms the structural frame behind the external walls.
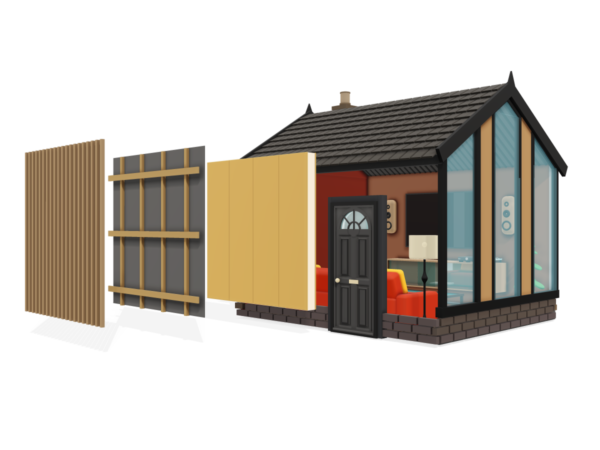
Buildings constructed using structural insulated panels.
Properties built using manufactured components or particular concrete construction systems.
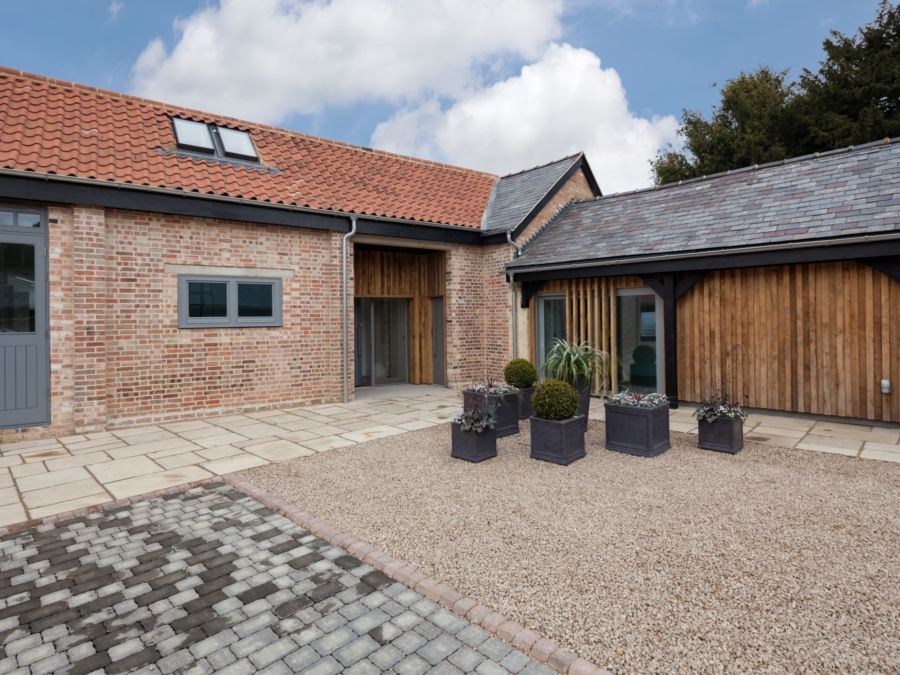
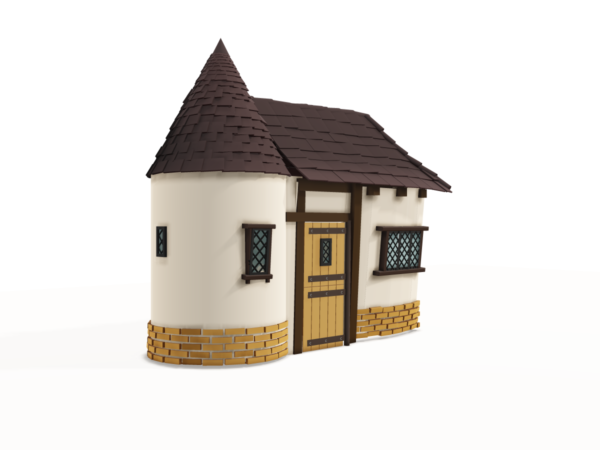
Homes using materials such as cob or wattle and daub, or combining different construction methods.
Properties with a partly or entirely flat roof, including felt, asphalt, rubber or fibreglass coverings.
Properties assessed according to their construction materials, structural system and roof type.
You can arrange buildings insurance on its own or combine it with contents insurance.
Buildings cover protects the structure of your home against insured loss or damage. Contents cover protects the belongings you keep inside it.
Having the details of your property ready can make the quote easier to complete. You may be asked for:
A brick or rendered exterior may conceal a timber or steel frame. Check your survey, construction drawings or building records if you are unsure.
For help identifying the structure, read our guide to non-standard construction.
If the quote asks for a percentage breakdown, our construction-percentage guide explains when one construction category can be entered as 100% and when a mixed-construction home needs a split.
Family Legal Protection Plus extends this cover limit to £50,000 and increases the range of legal disputes that you’re covered for.
Enjoy complete protection with extended emergency callout cover with up to £1,000 per callout, £1,000 Total Claims Limit/Year, Boiler & Heating System cover & Alternative Accommodation
Cover for accidental breakages or damage to your buildings e.g: putting your foot through the ceiling, or accidental breakage of glass
Tell us about your property’s construction and the cover you need.
Speak to our team if you are unsure how to describe your home or complete the quote.
You can start a quote online by providing your property and insurance details. Some construction types or circumstances may need further information or individual consideration. Contact our team if you need help completing a question.
It can be, but a higher premium is not automatic. The price depends on the property’s construction, rebuild cost, location, condition, use and claims history, alongside the cover selected and the insurer’s assessment.
Yes. Brickwork can form the external surface of a home with a timber or steel structural frame. Describe the construction using the information available in your survey or building records, rather than relying only on its appearance.
Check your building survey, construction drawings or information from the builder or developer. If the construction remains unclear, professional confirmation may be needed. Our team can help explain the quote questions, but cannot confirm your home’s structure remotely.
Not always. If a single construction category describes the whole property, you may be able to enter 100% for that category. Homes combining different construction methods may need a split. Our construction-percentage guide explains the quote options.
Not necessarily. An insurer’s willingness to insure the property does not confirm cover for every feature or installation. Tell us about the features your home has and check how the policy treats them before purchasing.
Understand your construction, prepare your quote details and check your rebuild cost.
Find out when to enter 100% for one construction category and how to describe a home built using different methods.
Explore common construction types and learn how to identify the structure of your own home.
Understand why rebuild cost differs from market value and when you may need specialist advice.
“The insurance cover we required was outside the ordinary and we were delighted to have chosen Intelligent Insurance. Their web site was simple to understand and use, we answered the questions, completed the form and received a quote that suited us.”
If you’re currently insured with us, you’ll find the documents for your policy in MyAccount.
Making a claim has never been easier – just follow these three simple steps:
Find your insurer’s claims contact details in your policy document or Schedule. Always have your policy number to hand, as it helps your insurer’s claims team quickly identify you and assist you without delay.
Call your insurer’s claims team as soon as the incident occurs. Provide a brief description of what happened and, if applicable, notify the Police within seven days for incidents like theft or malicious damage.
If required, complete and return the claim form along with supporting documents (receipts, photos, etc.) within 30 days. This ensures a smooth, timely processing of your claim.
*We may not be able to quote in all circumstances. Cover limits/restrictions and/or conditions may apply to the policy. These are clearly detailed prior to purchase, and in the policy documentation for you to determine if the cover is suitable for your needs.