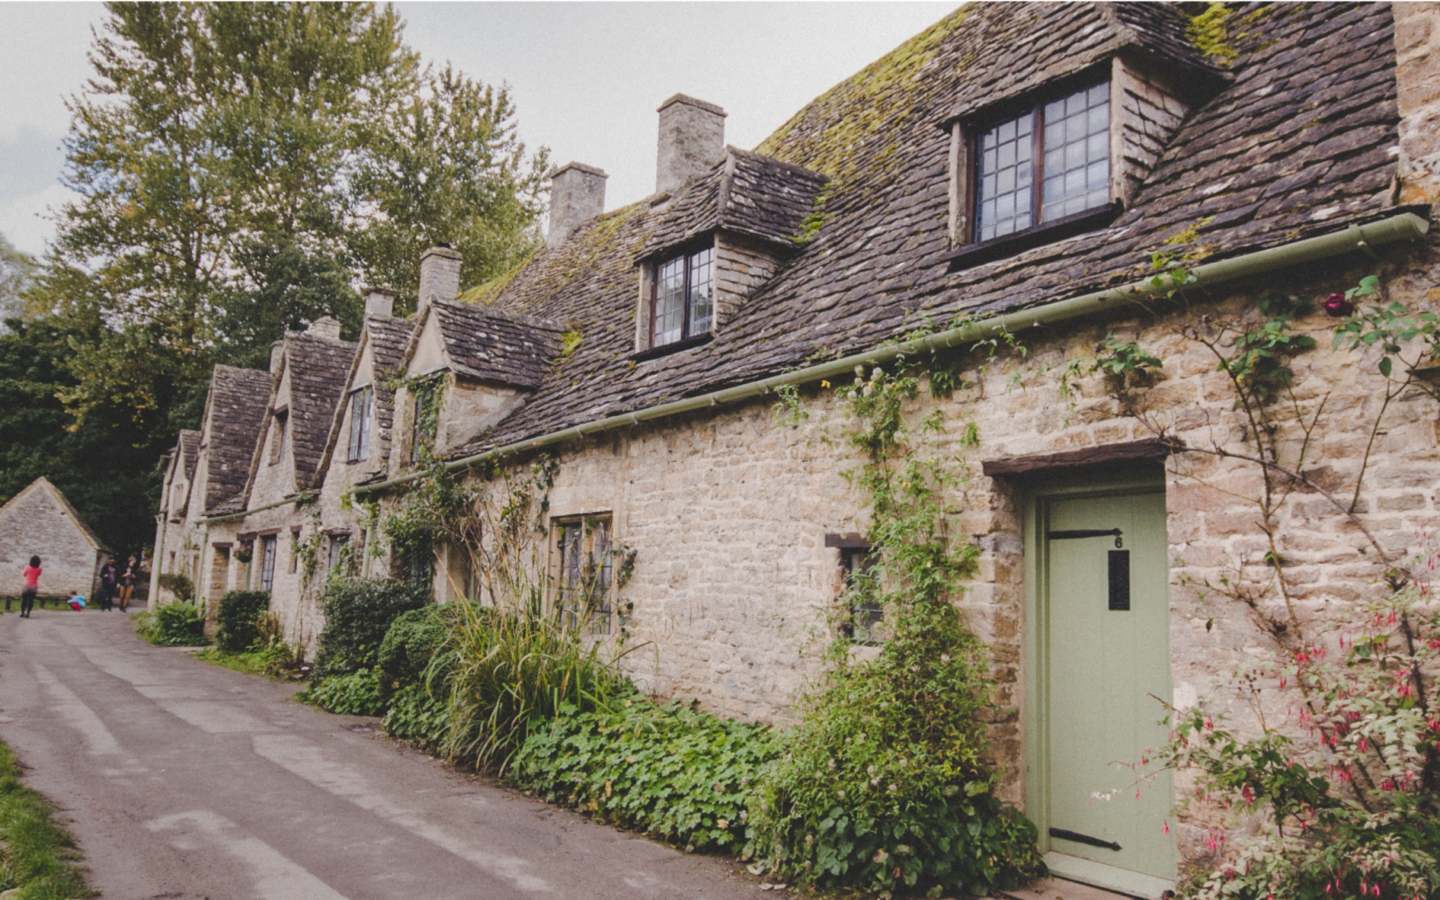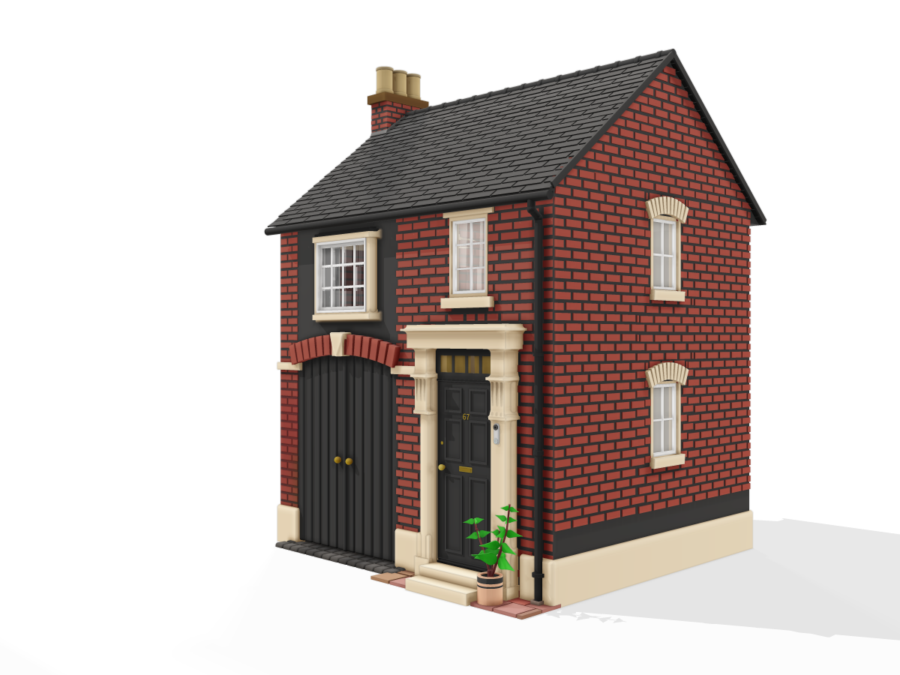
3D illustration of a red-brick coach house with living accommodation above an integral garage.
Home insurance for your coach house

Coach house insurance

A coach house can come with a few extra insurance questions, especially when neighbours use the garages or access beneath your home.

At Intelligent Insurance, we help arrange buildings and contents cover for coach houses through our panel of insurers. We can also consider properties with garages used by neighbours.

What is coach house insurance?

Coach house insurance is home insurance arranged for a coach house, which may have living accommodation above garages, carports or an access passage through the building. It can provide buildings cover for the insured structure and contents cover for your belongings.

The layout and ownership arrangements matter. Some owners use all the spaces beneath their home, while others have garages or access routes used by neighbours. Your policy should reflect the parts of the building you’re responsible for insuring.

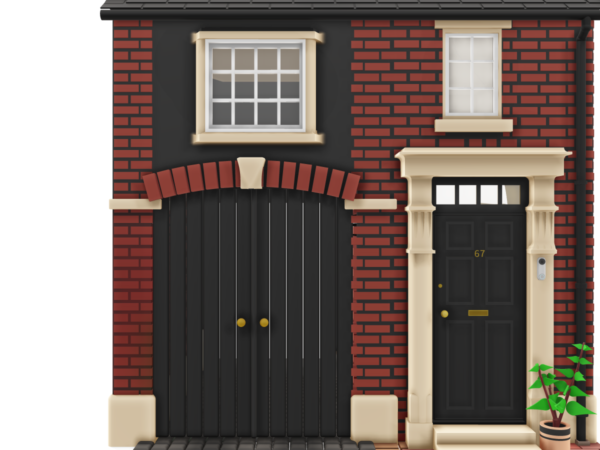
Close-up illustration of a coach house showing arched garage doors beside a separate front entrance

Can I insure a coach house if my neighbours use the garages underneath?

Yes. We can consider coach houses where neighbours use one or more garages beneath the home, including where they have the right to use a garage under a lease.

For example, your home might sit above three garages. You use one and two neighbours use the others. If you’re responsible for insuring the whole building, the buildings cover needs to account for that arrangement, including the garages and the structure supporting your home.

Our team can check which parts of the building the insurer can include. The quote and policy documents will set out the cover offered.

Get a Quote
Buildings, contents and additional protection

What can coach house insurance cover?

Cover options can include the benefits below. Your quotation will show the cover available for your property, the limits, excesses and any specific conditions.

Read it alongside the policy wording before you buy.

What we provide

Buildings cover up to £1,500,000, with the option to increase for specific cases
The amount your insurer will pay to repair or rebuild your home in the event of an insured loss
Contents Insurance up to £125,000
New for old cover for belongings kept in your second home
Alternative accommodation
Cover towards temporary accommodation following insured damage that makes the property uninhabitable, subject to the policy’s terms
Replacement locks and keys
Cover for replacement locks and keys in the circumstances
Trace and access cover up to £5,000
Cover towards the cost of accessing an insured water leak and making good the resulting damage
Family Legal Protection up to £25,000
Cover for legal expenses (whether prosecuting or defending). There is a £100 excess.

What isn't included?

We don’t cover loss or damage
The policy does not cover every cause of loss or damage. The current cover summary lists exclusions including:
  • Wear, tear and gradual deterioration, or damage that happened before cover began.
  • Loss or damage caused by dishonest, deliberate or wilful acts, and other exclusions in the policy wording.
  • Cover beyond the limits shown in the policy schedule; excesses are payable when applicable.
  • Any specific restrictions or conditions shown by endorsement, including those relating to occupancy or time spent empty.
  • Letting, building work or a change in who lives at the property unless the insurer has assessed the arrangement and confirmed the applicable terms.
Cover restrictions
  • you are only covered up to the maximum claims limits shown on your schedule
  • you are responsible for any excesses stated in your policy
  • any exclusions or restrictions shown by endorsement in your schedule
  • The quotation and policy documents take precedence over this summary.

What will we need to quote for your coach house?

About your home

Have the address, construction details, rebuild cost and claims history to hand, along with the buildings and contents cover you need. Let us know whether it’s your main home, a second home or a property you let out, and when you want cover to start.

The rebuild cost should reflect the full cost of rebuilding the parts of the property to be insured, including any garages beneath your home that form part of that cover.

About the spaces underneath

Tell us about any garages, carports or access passages beneath the home, who owns or uses them, and who is responsible for insuring the structure. Include any shared driveway or pedestrian access through the building.

If you’re unsure, check the title documents and any leases. Your conveyancer can help explain the arrangement if you’re buying.

Optional cover for additional protection

You may be able to add extra protection when arranging your policy. Availability, cost and terms will be shown in your quotation.

Accidental Damage

Additional protection for accidental damage to your buildings, subject to the cover selected and policy exclusions.

Home Emergency Plus

An optional upgrade with higher claim limits and extra cover for specified heating, security and access emergencies in your main home.

Family Legal Protection Plus

An optional upgrade with a higher cover limit and a wider range of specified legal disputes, subject to the policy’s terms and exclusions.

Coach house insurance FAQs

Insurers can use different property categories for coach houses. If the options on a quote form don’t clearly describe your home, ask our team which category to use before you continue.

The price depends on the property’s location, construction, rebuild cost, claims history and the cover selected. The layout and garage or access arrangements may also affect the insurer’s assessment. A quote based on your property will show the premium and terms available.

Some coach houses have an access passage beneath the living accommodation. This might provide vehicle or pedestrian access to garages, parking or properties behind the building.

Explain the layout when you enquire, including who uses the passage, so we can check the insurance options for your property.

The lease and title documents should set out who is responsible for arranging buildings insurance and what it needs to cover. Ask your conveyancer to explain any unclear terms before arranging cover.

Cover for your belongings in a garage depends on the contents policy, including any claim limits and security requirements.

Buildings cover for a garage concerns its structure. It doesn’t by itself insure the belongings stored inside.

Yes. You can enquire before the purchase is complete. Have the property details and proposed cover start date ready. Your conveyancer can confirm when buildings insurance needs to begin for your purchase.

Still have questions? Visit our help centre

Arrange insurance for your coach house

We’ve helped coach house owners arrange home insurance, including for properties with garages used by neighbours.

Speak to our team about the cover you need.

  • Defaqto 5-Star rated protection
  • Buildings and contents cover options
  • Access to a panel of specialist home insurers
  • Help from our team with your insurance questions
Get a home insurance quote
Get a quote
Need to discuss your property?

Chat with a member of our team.

Live Chat

Guides for coach house owners

Practical guidance on rebuild costs, construction and arranging home insurance.

Green ‘i’ beside a question mark, illustrating questions about specialist home insurance brokers.
Why Use a Specialist Home Insurance Broker?

What does a specialist home insurance broker do? Learn when their help may be useful and how the broker route compares with comparison sites and buying direct.

How to make a claim for your coach house.

Making a claim has never been easier – just follow these three simple steps.

step-one

Step One – Check Your Policy

Find your insurer’s claims contact details in your policy document or Schedule. Always have your policy number to hand, as it helps your insurer’s claims team quickly identify you and assist you without delay.

step-two

Step Two – Report the Incident

Call your insurer’s claims team as soon as the incident occurs. Provide a brief description of what happened and, if applicable, notify the Police within seven days for incidents like theft or malicious damage.

step-three

Step Three – Submit Your Claim

If required, complete and return the claim form along with supporting documents (receipts, photos, etc.) within 30 days. This ensures a smooth, timely processing of your claim.

*We may not be able to quote in all circumstances. Cover limits/restrictions and/or conditions may apply to the policy. These are clearly detailed prior to purchase, and in the policy documentation for you to determine if the cover is suitable for your needs.

Home Insurance Specialists names you can trust

Intelligent Insurance | Non-Standard Home Insurance
Intelligent Insurance | Pen Underwriting Panel Member
Custom Home by Intelligent Insurance
Intelligent Insurance | Arkel Panel Member
Intelligent Insurance | Prestige Underwriting Panel Member
Nelson policies as Lloyd's logo

Get Your Second Home Insurance Quote Today

Get a quote