Back to Blog

Can You Use a Listed Building as a Filming Location? What Homeowners Need to Know About Insurance

Using a listed home as a filming location introduces risks that ordinary household use does not. Discover what to check before allowing a production crew into your property.

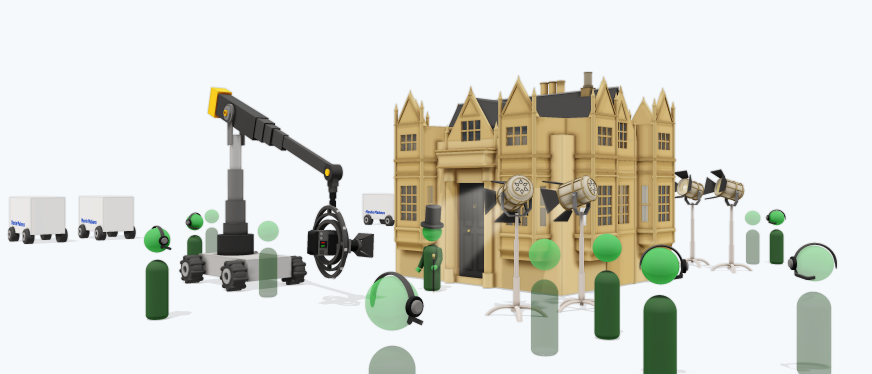
Illustration of a film crew, camera crane and studio lights surrounding a listed country house used as a filming location.

From period dramas and television advertisements to magazine shoots and feature films, characterful historic homes regularly provide the backdrop for productions across the UK.

For owners, hiring out a listed property can offer additional income and the unusual experience of seeing their home appear on screen.

However, a production can involve considerably more than a camera and a handful of actors. Film crews bring lighting equipment, temporary power supplies, set dressing, specialist vehicles and dozens of people into a building that was not designed to operate as a commercial production space.

If your home is listed, the risks can be particularly significant. Original floors, decorative plasterwork, historic staircases and other protected features may be difficult and expensive to repair.

Before agreeing to any filming, it is important to understand how the arrangement could affect your home insurance, what the production company’s insurance actually covers and whether proposed changes require additional permissions.

Can a listed home be used as a filming location?

Yes. Listed buildings can often be used for filming, photography and television production, provided the activity is properly managed and any necessary insurance, permissions and safeguards are in place.

A property does not need to be a stately home to attract a production company. A Georgian townhouse, thatched cottage, Victorian villa or characterful period farmhouse might also suit a particular film, television series or advertising campaign.

However, listed status means the building’s historic features may need additional protection. Depending on the property, this can include:

  • Original timber floors and staircases.
  • Decorative ceilings and plasterwork.
  • Historic fireplaces and panelling.
  • Period doors, windows and shutters.
  • Traditional stonework, brickwork or roofing.
  • Historic outbuildings, walls and garden features.
  • Valuable furniture, artwork and antiques.

The key question is not simply whether filming is allowed. It is whether the property, production arrangements and insurance cover are suitable for what is being proposed.

Do you need to tell your home insurance provider?

You should speak to your insurer or broker before agreeing to filming at your property.

A residential home insurance policy is normally arranged based on how the property is used, who has access to it and the risks associated with day-to-day occupation.

Using the home as a commercial filming location can change those circumstances.

Government guidance explains that home insurance may not cover business activities or visitors attending a property for business purposes. Whether filming affects cover depends on the policy wording, the nature of the production and the insurer’s underwriting requirements. See GOV.UK guidance on running a business from home.

Your insurer or broker may ask:

  • Is the filming a one-off event or a regular arrangement?
  • Will you receive payment for the use of your home?
  • How many crew members, performers or contractors will attend?
  • How long will the production be on site?
  • Are preparation and dismantling days included?
  • Which parts of the house, grounds or outbuildings will be used?
  • Will furniture, artwork or antiques be moved?
  • Will the production involve generators, lighting rigs, catering equipment or temporary structures?
  • Are any changes planned to the building or its fixtures?
  • Will you remain in the property throughout the shoot?

A one-off production does not automatically invalidate your policy. However, assuming your existing cover applies without checking could leave important gaps or create difficulties if damage occurs.

What risks can filming introduce?

Film and television productions involve equipment, people and working practices that are very different from normal domestic use.

For a listed home, even relatively minor damage can become complicated if specialist materials, conservation advice or skilled craftspeople are needed.

Potential risk What could happen
Increased footfall Repeated movement through corridors, staircases and rooms damages original flooring or fragile surfaces.
Equipment and furniture Camera cases, lighting stands or moved furniture strike panelling, doors, walls or decorative plasterwork.
Temporary cabling Cables create trip hazards, obstruct doorways or damage vulnerable floors and finishes.
Fire and electrical equipment Lighting, generators, batteries, temporary power supplies or catering equipment increase fire risks.
Set dressing Paint, fixings, adhesives or temporary installations damage historic features.
Security Doors are left open, access becomes harder to control or security systems are temporarily obscured.
Valuable contents Artwork, antiques or delicate furnishings are damaged, misplaced or stolen.
Gardens and grounds Production vehicles, cranes, catering units or generators damage lawns, driveways, boundary walls or landscaping.
Special effects Smoke, artificial rain, candles or other effects affect historic surfaces or introduce additional hazards.

The Health and Safety Executive identifies particular concerns with historic filming locations, including older electrical systems, inadequate fire protection, restricted access, uneven staircases and poorly lit areas. See the HSE guidance on buildings used as locations or temporary studios in film and television.

Fire risks deserve particular attention

Period properties can contain materials and construction features that make a fire more difficult to control.

Examples can include exposed timber, concealed roof spaces, older wiring and limited fire separation between rooms.

Filming may introduce further hazards through:

  • High-powered or heat-producing lighting.
  • Temporary electrical connections.
  • Generator placement.
  • Battery charging.
  • Catering equipment.
  • Candles, fireplaces or other naked flames.
  • Artificial smoke or special effects.
  • Fire doors being held open for cables or equipment.

Even where modern LED lighting reduces the heat generated by some equipment, electrical safety and battery charging still need proper consideration.

Any proposal involving flames, pyrotechnics, significant electrical work or changes to fire protection arrangements should be discussed with the relevant specialists and your insurer before the production takes place.

The risk starts before filming begins

Homeowners may focus on the day the cameras are rolling, but a production’s activities can extend well beyond the actual shoot.

Depending on its size, the process may include:

  1. An initial location visit or technical recce.
  2. Delivery of equipment and production vehicles.
  3. Set preparation and dressing.
  4. Installation of lighting and temporary power.
  5. Filming.
  6. Dismantling and removal of equipment.
  7. Cleaning, repairs and reinstatement.

Some of the greatest risks can arise when equipment is being carried through the property, furniture is being moved or production teams are working quickly to prepare or clear a location.

Rooms that do not appear on screen may also be used as changing areas, production offices, green rooms or storage spaces.

Hallways, staircases, bathrooms, kitchens, driveways and gardens can therefore experience considerable activity, even if the filming itself takes place in only one room.

Does the production company’s insurance cover your home?

A professional production company should have appropriate insurance for its activities.

Public liability insurance can cover certain claims arising from injury to other people or damage to third-party property. Film London explains that the amount of cover required depends on factors such as the size of the production, the location and the nature of the filming. See Film London’s media insurance guidance.

However, the existence of a public liability policy does not automatically mean every type of damage to your property or belongings will be covered.

The protection available will depend on the production company’s policy wording, exclusions, limits and the circumstances of the incident.

Before agreeing to a shoot, ask the production company or location manager:

  • What insurance is in place?
  • Does it specifically cover damage to hired filming locations?
  • Are listed features, historic interiors and valuable contents included?
  • Does the policy cover the full preparation, filming and dismantling period?
  • Are gardens, outbuildings and access routes included?
  • What policy limits and excesses apply?
  • Are particular activities or types of property excluded?
  • Who is responsible for arranging and paying for specialist repairs?
  • What happens if damage is discovered after the crew has left?

It is also important to understand that the production company’s insurance and your own buildings and contents insurance serve different purposes.

A production’s liability insurer may consider whether the company was legally responsible for the damage. Your own insurer will separately consider whether the incident falls within the terms and conditions of your home insurance policy.

Neither policy should be assumed to replace the other.

What should a filming location agreement include?

A written location agreement helps establish what the production company is permitted to do and who is responsible if something goes wrong.

A suitable agreement may address:

  • The dates and hours during which the production can access the property.
  • Any preparation, filming, dismantling and cleaning periods.
  • The rooms, grounds and outbuildings that may be used.
  • Areas that are strictly off limits.
  • The maximum number of people allowed on site.
  • Approved vehicle access and parking arrangements.
  • Any proposed set dressing, alterations or temporary installations.
  • Protection for floors, walls, furniture and other vulnerable features.
  • Insurance responsibilities and evidence of cover.
  • Arrangements for identifying, reporting and repairing damage.
  • Responsibility for cleaning and reinstatement.
  • Security arrangements during and after filming.
  • The treatment of valuable contents and personal belongings.
  • Whether the property can be identified publicly.
  • A named contact for resolving problems during the shoot.

For larger productions or particularly sensitive properties, the homeowner may also wish to seek professional legal advice before signing the agreement.

Avoid relying solely on informal assurances that the production will “take care of everything”.

How can you protect a listed home during filming?

Careful preparation can reduce the likelihood of damage and make disputes easier to resolve.

Photograph the property before the crew arrives

Create a dated photographic record of:

  • Floors, walls and ceilings.
  • Staircases and doorways.
  • Furniture, artwork and antiques.
  • Windows, fireplaces and decorative features.
  • Driveways, lawns and garden structures.
  • Any rooms used for storage, changing or catering.

Share the record with the production company before filming begins.

Repeat the inspection after the crew has left, ideally before any agreed handover is completed.

Identify fragile or protected features

Explain which features must not be touched, moved, covered or attached to.

Where appropriate, arrange suitable protective coverings for floors and vulnerable surfaces. Any protection should be compatible with historic materials and should not cause damage when removed.

Agree access routes

Decide in advance how equipment will enter and leave the building.

A narrow staircase or historic doorway might not be suitable for large lighting cases, camera equipment or heavy furniture.

Where possible, keep the movement of equipment away from the most sensitive parts of the property.

Secure valuable contents

Consider whether valuable or fragile items should be moved before filming.

If antiques, paintings or other belongings are transported or stored elsewhere, check whether your contents insurance applies while they are away from the property.

Specialist removal or storage arrangements may be appropriate for particularly valuable items.

Keep safety responsibilities clear

The production company will generally be responsible for managing the health and safety risks created by its work.

However, homeowners should make the company aware of any known property hazards, such as uneven steps, fragile floors, restricted access or potentially unsafe areas.

The Health and Safety Executive advises productions to define responsibilities, assess risks and review safety arrangements as work progresses. See the HSE’s guidance on safety in film, TV and broadcasting.

Check your rebuild and contents values

Listed buildings can require specialist materials, traditional construction methods and skilled craftspeople following an insured loss.

Before allowing commercial activity on the premises, it may be sensible to review whether your buildings and contents cover still reflects the property and its features.

Our rebuild cost guide explains why the cost of reinstating a property can differ significantly from its market value.

Does regular filming change your insurance requirements?

It can.

A one-off photography shoot may be assessed differently from a property that is regularly marketed and hired as a filming location.

If commercial productions use your home frequently, your insurer may consider:

  • How often the property is hired.
  • Whether location work provides regular income.
  • The number of visitors and contractors attending.
  • Whether the house remains primarily residential.
  • Whether parts of the property are used for commercial activities.
  • The type and scale of productions accepted.
  • Whether additional liability protection is needed.

Some situations may require specialist insurance arrangements that go beyond a standard residential policy.

Regular filming could also raise separate questions about contracts, planning, mortgage conditions or tax. If location hire becomes a recurring business activity, seek appropriate professional advice.

Protecting your listed home before the cameras roll

Using a listed home as a filming location can be a rewarding opportunity, but the arrangement needs careful planning.

Before agreeing to a production, speak to your insurer or broker, understand the production company’s insurance, check whether any proposed work requires permission and make sure responsibilities are clearly recorded in writing.

A listed property’s historic features are often the reason it attracts filmmakers in the first place. Protecting those features should be part of the production plan from the outset.

At Intelligent Insurance, we help homeowners arrange cover for listed and other non-standard properties. If you own a listed home, speak to our team about your circumstances before allowing commercial filming to take place.

Find out more about listed building insurance.

Frequently asked questions

Do I need to tell my insurer if my home is used for filming?

Yes, you should speak to your insurer or broker before agreeing to filming. Commercial productions can introduce additional risks, and your insurer may need details about the number of people attending, the equipment involved and how long the production will use the property.

Does a film crew’s public liability insurance cover damage to my home?

It may cover certain claims if the production company is legally responsible for damage, but cover depends on the policy wording, exclusions and limits. It should not be treated as a replacement for your own buildings and contents insurance.

Do I need listed building consent for filming?

Filming itself does not automatically require listed building consent. However, consent may be necessary if the production intends to carry out work affecting the property’s historic character or protected features.

Can a film crew temporarily repaint a listed room?

Possibly, but permission may be required depending on the room, the existing finishes and the significance of the proposed changes. Check with your local planning authority or conservation officer before agreeing to any repainting.

Is my home covered while the crew prepares or dismantles the set?

That depends on the relevant insurance policies and contractual arrangements. Confirm that any cover applies throughout preparation, filming, dismantling, cleaning and reinstatement.

What happens if an antique or artwork is damaged during filming?

Responsibility depends on how the damage occurred, the location agreement and the insurance policies involved. Identify valuable items before filming, check the relevant cover and consider moving fragile belongings to secure storage.

Can I regularly hire out my listed property as a filming location?

Potentially, but regular commercial use may affect your insurance requirements and could involve additional planning, contractual or business considerations. Speak to your insurer or broker before accepting repeat bookings.

Does it matter if the filming is unpaid?

Yes. Even if you do not receive a location fee, the activity may still introduce additional people, equipment and risks to your home. Your insurer or broker should assess the actual circumstances rather than the payment arrangement alone.

Read more